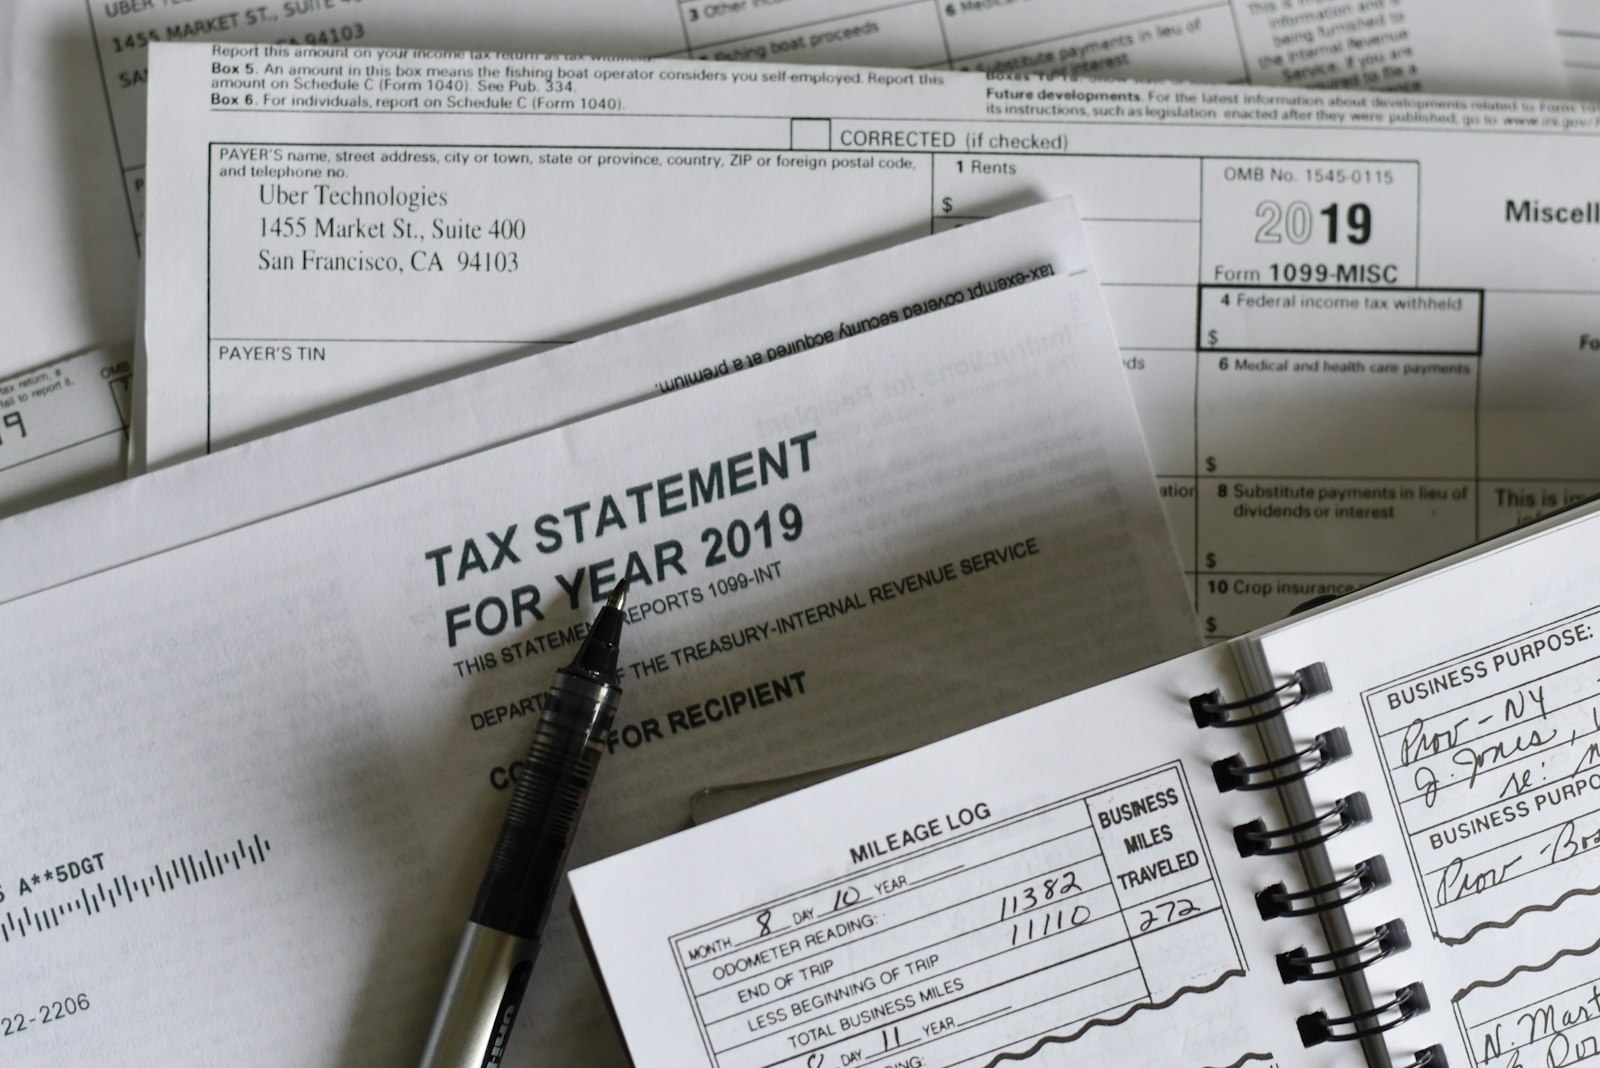
Tax debt has a psychology problem: the worse it gets, the harder it is to look at. Balances grow with penalties and interest, notices escalate, and paralysis feels safer than engagement. But here’s what two decades of resolution work teaches: the IRS has established, rule-based programs for every situation — and people who engage them do dramatically better than people who hide.
First: stop the bleeding
Whatever you owe, two moves come before everything else. File every unfiled return — the failure-to-file penalty (5% per month, up to 25%) dwarfs the failure-to-pay penalty (0.5% per month), and no resolution program will talk to you until you’re filing-compliant. And stay current on this year’s taxes, because new debt torpedoes any agreement about old debt.
Option 1: Pay in full (strategically)
If the balance is manageable, paying it ends the interest clock and the letters. Even here there’s strategy: verify the balance is actually correct first (they’re often not, especially after substitute-for-return filings), and pursue penalty abatement — see below — so you’re paying the real debt, not the inflated one.
Option 2: Installment agreements
The workhorse of tax resolution. Balances under $50,000 generally qualify for a streamlined agreement — up to 72 months, minimal financial disclosure, set up online or by mail. Larger balances require a full financial statement but remain very achievable. Collection activity generally pauses while an agreement is pending and in good standing. Interest continues, but levies stop — and life becomes plannable again.
Option 3: Offer in compromise
Yes, the IRS really does settle debts for less than the full amount — through a formula, not a negotiation trick. An OIC is evaluated on your reasonable collection potential: the equity in what you own plus what your income can spare over a defined period, per IRS expense standards. If that number is genuinely less than your debt, an offer can succeed. If it isn’t, no firm on earth can make the IRS accept one.
An offer in compromise is math, not mercy. The winning move is knowing whether your math works before you spend months and fees applying.
This is where honest advice pays for itself. We run the same calculation the IRS will, first. Sometimes the answer is “you’re a strong OIC candidate.” Just as often it’s “an installment agreement plus penalty abatement gets you out cheaper and faster.”
Option 4: Currently not collectible
When paying anything would genuinely prevent you from covering basic living expenses, the IRS can mark the account currently not collectible. Collection stops. The debt remains and interest accrues — but the ten-year collection statute keeps running, and for some taxpayers, CNC status quietly carries the debt to expiration.
Penalty relief stacks with everything
Whichever path fits, penalty abatement rides along. First-time abatement is close to automatic if you have a clean three-year compliance history — yet it goes unclaimed constantly because nobody asks. Reasonable cause relief covers serious illness, disasters, and other genuine hardships. On a large balance, abatement alone can erase thousands.
What about those TV companies?
The “fresh start hotline” industry charges large upfront fees, files boilerplate offers regardless of eligibility, and disappears when they’re rejected. The programs they advertise are real — they’re the same ones in this article, available to anyone. What you should pay for is judgment: which program, argued how, by someone who’ll still answer the phone in month six.
That’s what we do. Bring us your notices — the first look is free and confidential. Start today; the statute clock is already running in your favor.